

Reduction of Exit tax
One of the most welcome changes is the reduction of Exit Tax from 41% to 38%, marking an initial step in making investing more attractive for individual investors. This change lowers the tax payable on investment gains for those invested in funds promoted by life companies and exchange-traded funds (ETFs).
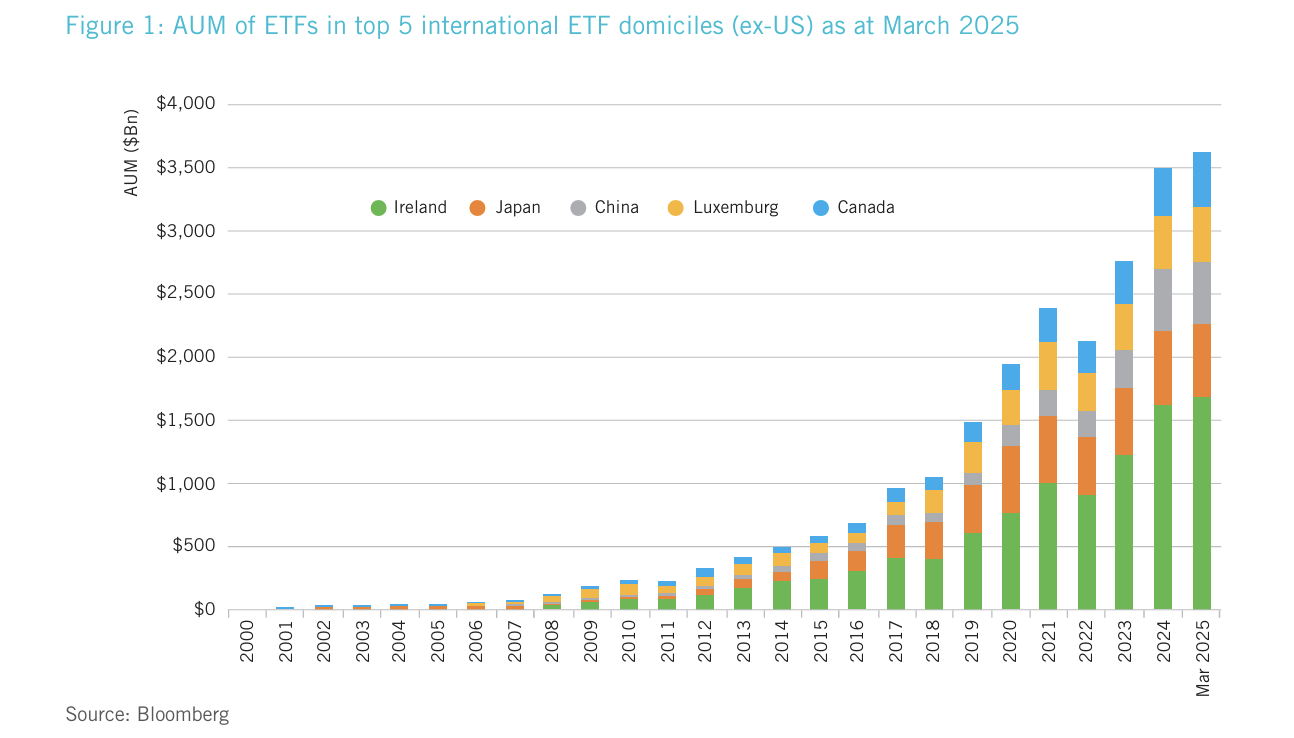
Ireland is a major centre for the administration of ETFs, with over thirty thousand jobs dependent on the fund administration sector. The Sunday Business Post recently reported that Irish-domiciled ETFs account for assets exceeding €1.35 trillion, representing 74% of all such assets in Europe. The irony for Irish investors is that the government has not encouraged personal investing in ETFs , even though we are a world centre for the administration of these funds.
What next?
The government have committed to publishing a comprehensive roadmap early next year to simplify and modernise the tax system around investing for individual investors. A positive outcome would see the following happen:
Revised Entrepreneur Relief
This was the standout positive from Budget 2026. The lifetime capital gains limit under revised entrepreneur relief has increased from €1m to €1.5m. The purpose of this relief is to reduce the capital gains tax (CGT) rate on the sale of certain business assets held by qualifying individuals. The word ‘qualifying’ is important. Entrepreneur relief can be complicated, so it's essential that you seek tax advice.
If you qualify, the CGT rate on the first €1.5 million of gains from the disposal of qualifying business assets is 10%, instead of the standard 33% CGT rate. If a business were sold at a gain of €1.5 million, under current rules*, you would pay CGT of €265,000. Once the new rules in Budget 2026 are adopted, the CGT liability in this scenario should be €150,000**, which may result in a potential CGT saving of up to €115,000.
For many people, selling or closing down their business is the culmination of a lifetime of work. Looking after existing employees, finding a buyer, and planning your future can be stressful. Good tax planning around revised entrepreneur relief can help smooth the transition, but it's important to seek advice early.
*€1M at 10%, balance of €500k at 33%- €100,000 + €165,000 = €265,000
** €1m at 10% = €100,000
Contact us today.
 +353 (0)87 344 5882
 info@saolcapital.ie
 Saol Capital, City Quarter, Lapps Quay, Cork T12 Y3ET
Registered in Ireland, company number 682955
Long Strand Limited trading as Saol Capital is regulated by the Central Bank of Ireland
© Copyright 2026 | Saol Capital | Software by REDStudio | All Rights Reserved
Contact us today.
+353 (0)87 344 5882
info@saolcapital.ie
Saol Capital, City Quarter, Lapps Quay, Cork T12 Y3ET
Registered in Ireland, company number 682955
Long Strand Limited trading as Saol Capital is regulated by the Central Bank of Ireland
Sustainable Finance Disclosure
© Copyright 2026 | Saol Capital | Software by REDStudio | All Rights Reserved